
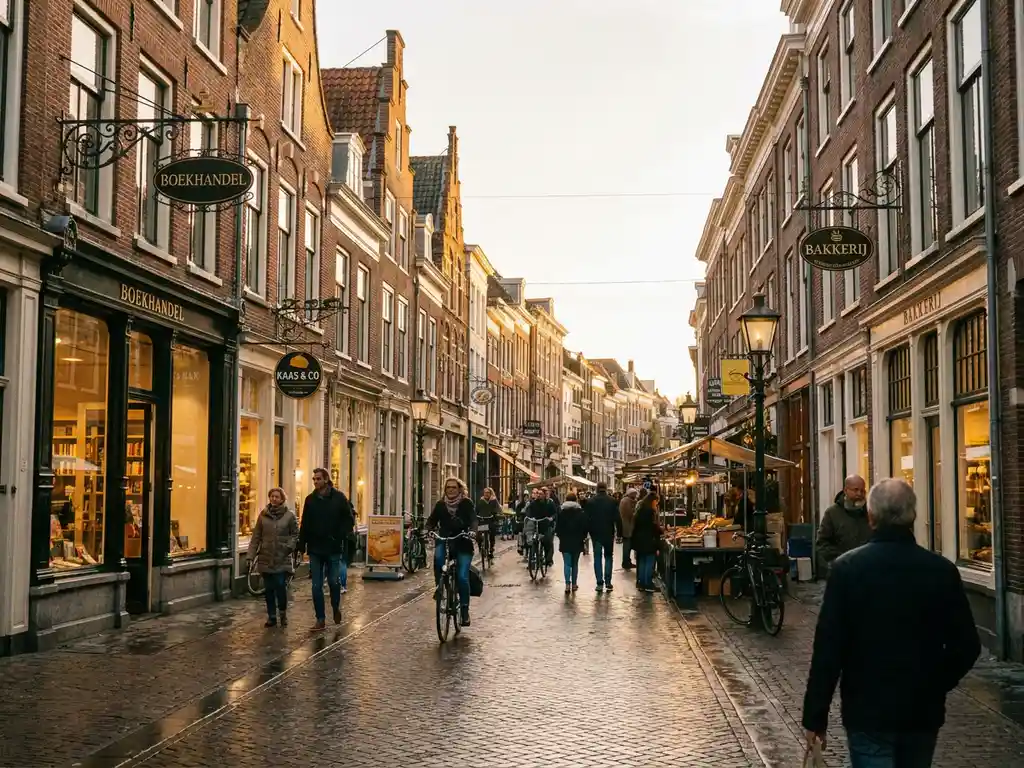
The outlook for retail real estate in the Netherlands in 2026 is cautiously positive, with investment volumes having risen sharply in 2025 and renewed institutional interest in prime assets. The market is bifurcating clearly: well-located, high-footfall retail in dominant cities and formats is performing strongly, while secondary locations continue to face structural headwinds. The sections below unpack the specific questions international investors are asking right now.
Which retail locations in the Netherlands are still outperforming?
The strongest performing retail locations in the Netherlands are prime high streets in the four major cities, Amsterdam, Rotterdam, Utrecht and The Hague, alongside dominant regional shopping centres with strong anchor tenants. Within these cities, the gap between A1 locations and secondary streets has widened considerably, making location selection the single most important variable in Dutch retail investment.
Amsterdam’s PC Hooftstraat and Kalverstraat remain among the most liquid and sought-after retail streets in Northern Europe. Vacancy on these streets is structurally low, tenant demand from international luxury and fashion brands is consistent, and rental income has proven resilient even through periods of broader market softness. Rotterdam’s Lijnbaan and Koopgoot, Utrecht’s Lange Elisabethstraat, and The Hague’s Spuistraat similarly attract strong occupier demand.
Beyond the four major cities, the picture is more nuanced. Eindhoven, Groningen, Arnhem and Maastricht all have dominant high street pitches that continue to perform, supported by strong catchment populations and limited competing retail supply. What distinguishes outperforming locations is not just footfall volume but catchment quality, transport connectivity, and the absence of competing retail development nearby.
Understanding which specific streets within a city qualify as A1 is where local intelligence becomes critical. The difference between an A1 pitch and a B-location two streets away can translate into a 200 to 300 basis point yield difference and a fundamentally different vacancy risk profile. Dutch retail market research that goes to street level, rather than city level, is essential for making that distinction accurately.
What is happening to retail rents in the Netherlands?
Dutch retail rents are diverging sharply by location and format. Prime high street rents in Amsterdam and other dominant cities have stabilised or shown modest growth, while rents in weaker locations have continued to decline as landlords compete to retain or attract tenants. The overall market is not in freefall, but it is not a rising-tide environment either.
Dutch retail leases are typically indexed annually to the CPI, which means that in an inflationary period, headline rents have moved upward mechanically. However, the more meaningful indicator is whether market rents, the rents achievable on a new letting today, are above or below the contractual rent passing. Properties where the passing rent exceeds current market rent are described as overhuurde assets, and these carry meaningful risk at lease expiry.
For investors, the key question is not just what rent is being paid today but what rent is sustainable over the next lease cycle. That requires current letting market intelligence, not just historic transaction data. KroesePaternotte’s active involvement across both retail leasing and investment transactions means its market rent assessments reflect what is actually achievable in the current occupier market, not what was agreed three years ago.
What retail formats are attracting the most investor demand?
In 2026, the retail formats attracting the strongest investor demand in the Netherlands are standalone supermarkets, prime high street units in dominant cities, and food-anchored convenience retail. These formats share a common characteristic: they are either e-commerce resistant or benefit from the shift in consumer behaviour toward experience and necessity-based spending.
Standalone supermarkets have become a preferred asset class for institutional investors because they offer long leases, strong covenant tenants, and structural demand driven by population growth and housing development. The Dutch supermarket sector is dominated by a small number of well-capitalised operators, and a supermarket anchor in a convenience retail scheme provides a level of income security that discretionary retail cannot match.
Prime high street retail in dominant locations attracts demand from investors who understand that the best pitches in the Netherlands have a scarcity value that protects against long-term vacancy risk. Shopping centres continue to attract interest, but selectively: only truly dominant centres with strong footfall data and a differentiated tenant mix are considered investable by institutional capital. Secondary and tertiary shopping centres remain largely out of favour.
How does Dutch lease law affect retail property returns?
Dutch lease law has a direct and material impact on retail property returns, and it differs significantly from lease frameworks in the UK, Germany, or France. International investors who underestimate these differences risk mispricing assets or encountering unexpected income disruption at key lease events.
The standard lease term and break structure
Dutch retail leases are typically structured on a 5+5 year basis, with the first term of five years followed by an optional extension. Unlike UK leases, Dutch law provides tenants with significant protection against non-renewal, and landlords cannot recover possession without justifiable legal grounds. This tenant protection is a feature of Dutch law that affects how vacancy risk should be modelled at lease expiry.
The Article 303 rent review process
The most consequential Dutch-specific mechanism for investors is the Article 303 market rent review, known as huurprijsherziening. Either party can request a market rent review at the end of a lease period, and the new rent is determined by reference to comparable transactions over the preceding five years. This means that in a falling rental market, a landlord may face a court-imposed rent reduction, regardless of the contractual indexation that has been applied annually.
Correctly assessing exposure to Article 303 reviews requires access to a comprehensive comparable transaction database. KroesePaternotte’s rent review and valuation practice draws on lease transaction data going back to 1984, covering virtually the entire Dutch retail market. This depth of comparable evidence is what makes a defensible rent review position possible, and it is not something a generalist adviser can replicate.
What are the biggest risks in Dutch retail real estate right now?
The biggest risks in Dutch retail real estate in 2026 are overhuurde assets, structural location weakness, e-commerce displacement in discretionary retail categories, and mispriced yield assumptions at acquisition. Each of these risks is manageable with the right due diligence, but each has been underestimated by investors entering the market without adequate local intelligence.
- Overhuurde risk: Assets where passing rent exceeds current market rent face income correction at lease expiry. In a market where rents in secondary locations have declined, this risk is more widespread than headline figures suggest.
- Location bifurcation: The gap between A1 and B-locations in the Netherlands is extreme. An asset that looks attractively priced may be cheap for a reason. Street-level vacancy data and footfall trends are essential inputs, not optional.
- E-commerce displacement: Categories such as electronics, books, and mid-market fashion face ongoing structural pressure from online retail. Tenant mix analysis needs to assess not just current covenant strength but the medium-term resilience of the retail category.
- Yield mispricing: Dutch retail property yields vary significantly by format, location, and lease structure. Applying a generic yield to a Dutch retail asset without understanding the specific income risk profile leads to overpayment or missed opportunity.
- Tenant concentration: Single-tenant assets or schemes with a dominant tenant carry concentration risk. Assessing the financial strength and expansion plans of key tenants requires current occupier market knowledge.
Should international investors consider Dutch retail real estate in 2026?
Yes, but selectively and with local expertise. The Netherlands offers a stable legal framework, a transparent property market, high consumer spending power, and a dense urban population that supports retail demand in dominant locations. For international investors building a European retail portfolio, Dutch retail real estate offers genuine diversification and, in the right assets, attractive risk-adjusted returns.
The case for Dutch retail is strongest in prime high street assets in the four major cities, standalone supermarkets, and food-anchored convenience schemes. These formats offer income resilience, strong tenant covenants, and structural demand that is not dependent on discretionary consumer confidence. Investment volumes rose 61% in 2025, and the pipeline of institutional-quality assets coming to market in 2026 reflects renewed seller confidence.
The risks are real but navigable. The key is understanding Dutch-specific dynamics, particularly lease law, the Article 303 rent review mechanism, and the granular difference between strong and weak locations, before committing capital. International investors who have tried to apply their home market frameworks to the Dutch market without local guidance have paid for that gap in knowledge.
Working with a specialist who operates simultaneously across leasing, investment, and valuations provides a level of current market intelligence that generalist advisers cannot offer. Retail investment advisory from a firm with four decades of Dutch market transactions behind it is not a luxury for international capital entering this market. It is the most reliable way to assess whether an asset is correctly priced, what the re-letting potential looks like, and what the realistic yield trajectory is over the hold period.
For investors who want to understand the Dutch retail market before committing to a specific asset, KroesePaternotte’s background and market position reflects the kind of specialist depth that this market rewards. The Netherlands is not a market to approach with generic data. It rewards those who have the right local partner.
Related Articles
- What are the benefits of a pop-up shop as a first step offline?
- How many locations are profitable for a growing retail chain?
- What is the difference between prime and secondary retail locations?
- Why does anchor tenant quality matter for retail investors?
- What data should you analyse before buying retail property in the Netherlands?
- How do market trends affect retail property investment decisions?
- Renting a small retail space in the city center: what should you look out for?
- How does the Dutch retail property transaction process work?
- Should international investors buy Dutch retail real estate in 2026?