
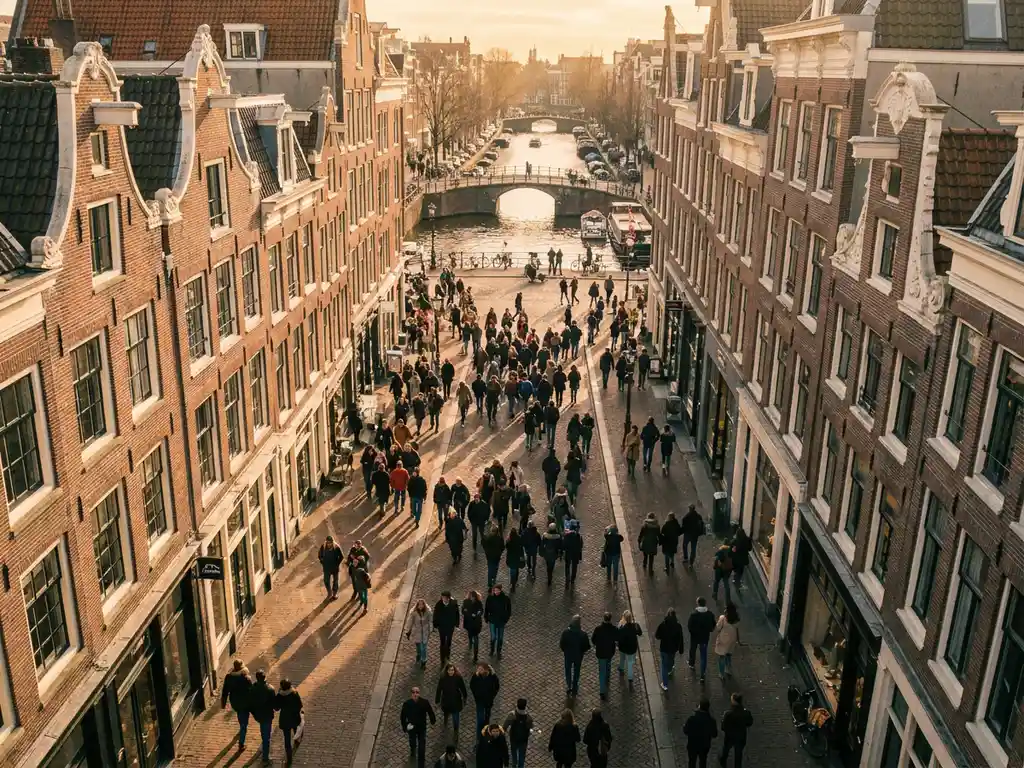
Footfall trends on Dutch shopping streets are polarised: prime high streets in major cities like Amsterdam, Rotterdam, Utrecht, and Den Haag have largely recovered and, in some cases, surpassed pre-pandemic visitor levels, while secondary and tertiary shopping streets continue to see structural visitor decline. The divergence is not temporary. It reflects deep shifts in consumer behaviour, retail formats, and the concentration of spending power in fewer, stronger locations. The sections below unpack which streets are moving in which direction, what is driving those shifts, and what footfall data means for anyone evaluating retail property in the Netherlands.
Which Dutch shopping streets have seen the biggest footfall shifts?
The strongest footfall recovery has been concentrated on A1 locations in Amsterdam, Utrecht, Rotterdam, and Eindhoven, where pedestrian counts have returned to or exceeded pre-2020 levels. Meanwhile, B and C streets in medium-sized cities and smaller regional centres have experienced sustained footfall losses, with some locations down significantly from their pre-pandemic peaks and showing no structural recovery trend.
Within Amsterdam, the Kalverstraat and Leidsestraat remain among the most visited retail corridors in the Netherlands. In Utrecht, the Lange Elisabethstraat and Steenweg consistently attract strong visitor numbers. Rotterdam’s Lijnbaan and the surrounding core have benefited from urban regeneration investment. Eindhoven’s retail heart, anchored by the Demer and Rechtestraat, has held up well relative to its size.
The contrast sharpens when you look beyond these urban cores. Many provincial high streets, particularly in cities with declining catchment populations or limited public transport connectivity, have seen footfall fall and not recover. In some cases, visitor counts are structurally lower because the retail offer has contracted: anchor tenants have left, vacancy has risen, and the street has entered a negative feedback loop where fewer visitors discourage new lettings, which further reduces the draw for visitors.
For investors, this polarisation is the defining feature of the Dutch retail real estate market. The difference between an A1 location and a B-location in the Netherlands is not marginal. It can mean the difference between a stable, income-generating asset and a structurally impaired one.
What is driving footfall changes on Dutch high streets?
Footfall changes on Dutch high streets are driven by a combination of e-commerce growth, shifting consumer preferences toward experience and convenience, urban demographic trends, and the concentration of retail investment in fewer flagship locations. No single factor explains the full picture, but together they are reshaping which streets attract visitors and which do not.
E-commerce penetration in the Netherlands is among the highest in Europe. Dutch consumers are comfortable buying online across most product categories, which has reduced the functional necessity of visiting a physical store for routine purchases. This has hit mid-market fashion and general merchandise streets hardest, while food, leisure, and experience-led retail have held up better.
Consumer behaviour has also shifted toward fewer but more purposeful shopping trips. When Dutch shoppers do visit a physical location, they tend to gravitate toward streets and centres that offer a strong, curated retail mix. This reinforces the performance of established prime streets and weakens the case for visiting secondary alternatives.
Urban demographics play a role too. Cities with growing, younger populations, strong student bases, and high tourist inflows, such as Amsterdam, Utrecht, and Groningen, have a structural advantage in sustaining footfall. Smaller cities with ageing or shrinking catchment populations face the opposite dynamic.
Finally, retailer location strategy has become more selective. International and national retailers are concentrating their physical presence in fewer, higher-performing stores. When a strong tenant exits a secondary street, it rarely attracts a like-for-like replacement, which accelerates footfall decline on that street.
How does footfall data affect retail property valuations in the Netherlands?
Footfall data is a direct input into retail property valuations in the Netherlands because it underpins the sustainability of rental income. A location with strong, stable, or growing visitor numbers supports current rent levels and reduces re-letting risk. A location with declining footfall signals potential rent pressure, higher vacancy risk, and downward yield adjustment, all of which affect asset value.
Dutch retail valuations follow RICS and NRVT standards, and a qualified valuer will assess footfall alongside lease terms, tenant covenant strength, and market rent evidence. Footfall does not appear as a line item in a valuation, but it informs the market rent assessment and the yield applied. A street with weakening visitor trends will typically attract a higher yield, reflecting the additional risk, which compresses the capital value of the asset.
For investors, this means footfall data is not just an operational metric. It is a leading indicator of valuation trajectory. A location where footfall is recovering ahead of the market may be underpriced relative to its improving fundamentals. Conversely, a location where footfall is quietly declining while rents have not yet adjusted may carry more risk than the current yield implies.
This is precisely where local market intelligence becomes critical. KroesePaternotte maintains a lease transaction database covering virtually the entire Dutch retail market going back to 1984, which allows for granular assessment of how rent levels on a given street have moved relative to footfall trends over time. That depth of data is what separates a defensible valuation from a generic estimate. You can explore the firm’s approach to this through their retail valuation and rent review services.
Are Dutch shopping centres outperforming high streets on footfall?
The picture is mixed. Dominant regional shopping centres with strong anchor tenants and a broad leisure and food offer have generally maintained or grown footfall. Smaller, convenience-focused centres have also performed well. However, mid-tier shopping centres without a clear identity or strong anchors have struggled, in some cases underperforming comparable high streets in the same catchment.
The strongest shopping centre locations in the Netherlands benefit from covered environments, easy parking, and a critical mass of tenants that creates its own visitor draw. Centres that combine a leading supermarket anchor with a curated mix of fashion, food, and services have proven resilient across economic cycles.
Where shopping centres have lost ground is in the middle tier: centres that are too large to be convenient but not large or distinctive enough to be a destination. These assets face structural footfall pressure as consumers choose either the convenience of online or the experience of a prime high street or dominant regional centre.
For investors assessing shopping centre assets, the key question is whether the centre occupies a dominant position in its catchment or sits in a more contested position. Dominance, defined by catchment share, anchor quality, and the absence of a credible competing centre nearby, is the single most important predictor of footfall resilience. KroesePaternotte’s retail market research covers catchment analysis and competitive positioning across the Netherlands, providing the granular location intelligence that investment decisions require.
What footfall levels signal a healthy retail investment location?
There is no universal footfall threshold that defines a healthy retail investment location, because the relevant benchmark depends on the city, the street type, and the retail format. What matters is whether footfall is sufficient to sustain the current tenant mix, whether it is stable or growing, and whether it compares favourably to competing locations in the same catchment.
A useful framework for assessing footfall health in the context of a Dutch retail investment considers three dimensions:
- Absolute level: Is the pedestrian count consistent with the rents being paid? High rents on a low-footfall street signal a mismatch that will eventually correct through vacancy or rent reduction.
- Trend direction: Is footfall stable, recovering, or declining? A street with modest but growing visitor numbers can be a stronger investment case than a busier street in structural decline.
- Relative position: How does this location rank within its catchment? A street that is clearly the dominant retail destination in its city is a more defensible asset than one competing with several alternatives of similar strength.
Beyond these dimensions, tenant quality is a strong proxy for footfall health. When national and international retailers with sophisticated location analytics choose to operate on a given street, it signals that their own data supports the location. Conversely, when established tenants exit and are replaced by temporary or lower-covenant occupiers, it often precedes measurable footfall decline.
Investors looking at the Dutch retail real estate market should treat footfall analysis as an integral part of investment due diligence, not a secondary consideration. The retail investment advisory team at KroesePaternotte integrates footfall intelligence with lease data, market rent benchmarking, and yield analysis to provide a complete picture of whether an asset is correctly priced for its location fundamentals.
Understanding footfall trends is ultimately about understanding which locations have a durable retail future and which are in structural retreat. In the Netherlands, where the gap between prime and secondary locations is particularly pronounced, getting that assessment right is the foundation of sound retail property investment. For investors who want the local intelligence to make that call with confidence, KroesePaternotte’s leasing expertise and investment advisory capabilities provide exactly that edge. Learn more about the firm and its track record at KroesePaternotte’s about page.
Related Articles
- What is the Dutch retail real estate market?
- What is the difference between a solitaire retail object and a shopping centre?
- How do you spot a retail property with growth potential in the Netherlands?
- What is the impact of online shopping on Dutch high streets?
- How does an energy label affect the rental price of commercial space?
- How does the Dutch retail property transaction process work?