
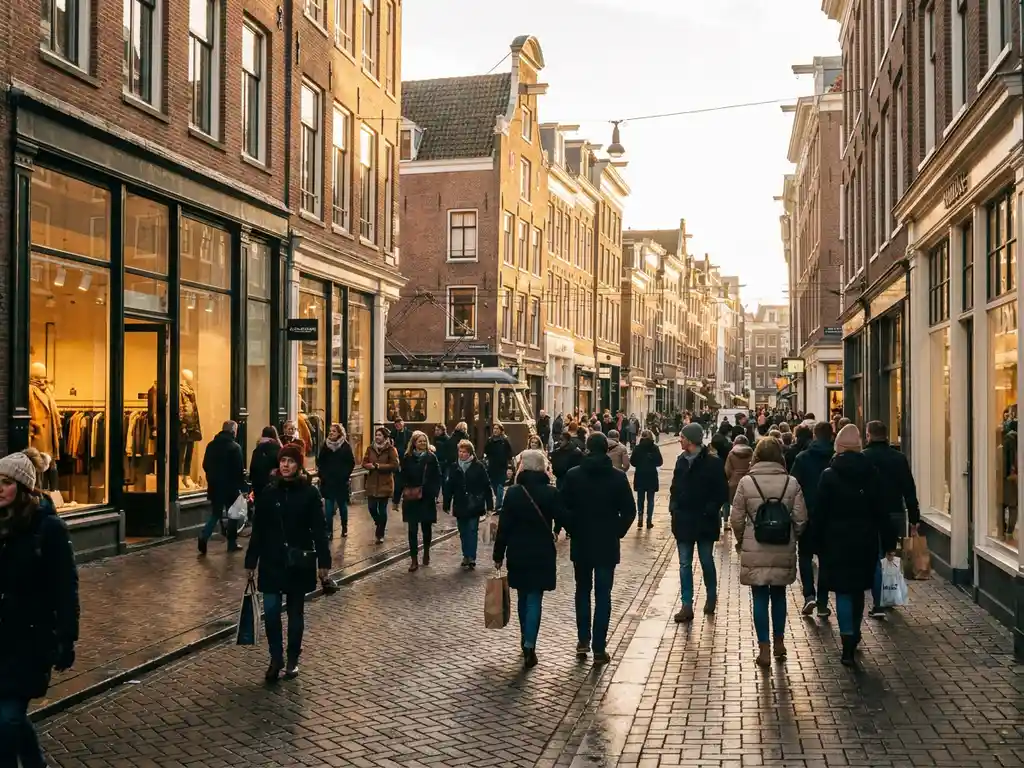
An A1 location in the Netherlands is the highest-grade retail street classification, designating the primary pedestrian shopping stretch in a city centre where foot traffic is at its peak, vacancy is minimal, and the strongest national and international retailers compete for space. The classification is not officially regulated but is widely used by retailers, investors, landlords, and advisors as a shared market standard. Understanding how Dutch location grades work is essential for anyone evaluating retail real estate in the Netherlands.
How are retail locations classified in the Netherlands?
Dutch retail locations are classified using a letter-and-number grading system that runs from A1 at the top down through A2, B1, B2, and C locations. The system reflects the commercial strength of a street or zone based on observable market factors: pedestrian flow, retailer demand, vacancy levels, and achieved rents. It is a practical market convention rather than a statutory designation, but it carries significant weight in leasing negotiations, valuations, and investment decisions.
The classification applies at the street level, and sometimes even at the block or unit level within a single street. A shopping centre or retail park is assessed separately and may carry its own grade based on catchment strength, anchor tenants, and trading performance. The grading is not static. Locations are reassessed informally by market participants over time as trading conditions shift.
For investors approaching the Dutch retail real estate market from outside the Netherlands, understanding this grading system is a prerequisite. The difference between a B1 and an A1 asset is not just a matter of rent level. It determines tenant quality, lease length, re-letting risk, and ultimately the defensibility of the yield. Dutch retail market research that maps these grades against actual transaction data is the foundation of any credible investment analysis.
What makes an A1 location different from an A2 location?
An A1 location is the single most trafficked and commercially desirable stretch of a city’s retail core, while an A2 location is the adjacent or secondary zone that connects to the A1 but sees measurably lower footfall and retailer demand. The distinction may appear subtle on a map but is significant in market terms.
On an A1 street, the mix of tenants reflects the strongest demand: international fashion chains, premium footwear brands, cosmetics retailers, and food-and-beverage concepts with national reach all compete actively for units. Vacancy on a genuine A1 is rare and typically short-lived. When a unit becomes available, it is often let before it reaches the open market.
On an A2 street, the tenant mix is broader and more variable. You will find solid national retailers and service concepts, but the depth of demand is thinner. Vacancy periods are longer, and the pool of tenants willing to pay A1-equivalent rents simply does not exist. Achieved rents on A2 locations can be 30 to 60 percent lower than on the adjacent A1, depending on the city and the specific street configuration.
For an investor, this distinction matters enormously when assessing re-letting risk. An A1 unit with a departing tenant carries limited downside because replacement demand is strong. An A2 unit in the same city may face a structurally different leasing environment, with longer void periods and potential rent concessions. Misclassifying an A2 as an A1 is one of the most common and costly errors made by investors without deep local knowledge of the Dutch retail leasing market.
Which Dutch cities and streets have A1 status?
A1 status exists in virtually every Dutch city with a functioning retail core, but the commercial weight behind that designation varies enormously between a major city and a smaller regional centre. Amsterdam, Rotterdam, The Hague, Utrecht, and Eindhoven carry the deepest A1 demand. Beyond those, cities such as Groningen, Maastricht, Arnhem, Nijmegen, and Breda have well-established A1 streets with genuine national retailer interest.
In Amsterdam, the Kalverstraat and Leidsestraat form the primary A1 axis, with the PC Hooftstraat functioning as a separate luxury A1 designation. Rotterdam’s Lijnbaan and Coolsingel corridor, The Hague’s Spuistraat and Grote Marktstraat, and Utrecht’s Lange Elisabethstraat and Steenweg are recognised A1 streets. In Eindhoven, the Demer and Rechtestraat carry A1 classification.
In smaller cities, an A1 designation may cover only a few hundred metres of a single street. The commercial depth behind it, meaning the number of retailers actively seeking space, is proportionally smaller. An A1 in Groningen or Breda is a strong location by local standards, but an investor should not assume it carries the same re-letting resilience as an A1 in Amsterdam or Utrecht. Granular, city-by-city knowledge is what separates a well-priced acquisition from an overpaid one.
KroesePaternotte maintains active leasing and investment coverage across all major Dutch cities, not just Amsterdam, and has built a lease transaction database going back to 1984 that covers virtually the entire Dutch retail market. That depth of data is what makes it possible to assess whether a street genuinely holds A1 status or whether that designation is being applied loosely in a sales context.
How does A1 location status affect retail rents and yields?
A1 location status directly drives the rent a tenant will pay and the yield an investor will accept. Prime rents on Dutch A1 streets are the highest achievable in the retail market, and yields on well-let A1 assets are compressed relative to secondary locations because investors price in lower vacancy risk and stronger income stability. The relationship between location grade, rent, and yield is the core pricing mechanism in Dutch retail real estate investment.
Rents on A1 streets in Amsterdam’s top locations rank among the highest in continental Europe. In secondary cities, A1 rents are lower in absolute terms but still command a clear premium over A2 equivalents in the same city. Dutch retail leases are typically indexed annually to the consumer price index, which means A1 rents compound over time in a way that supports income growth for investors.
Yields on A1 assets reflect the scarcity of supply and the depth of investor demand. In 2026, prime high street yields in the Netherlands remain competitive within the European context, with Amsterdam’s top streets attracting institutional capital from across Europe and beyond. The yield gap between A1 and A2 or B locations has widened in recent years as investors have become more selective, concentrating capital in locations where occupier demand is demonstrably strong.
The 303 rent review process, which governs market rent adjustments in Dutch retail leases, is another factor that connects location grade to investment returns. On an A1 street, a rent review is more likely to sustain or increase the passing rent because comparable evidence from recent lettings supports the level. On a weaker location, the same process may result in a downward revision. Understanding how Dutch lease law interacts with location quality is part of what makes retail property valuations and rent reviews in the Netherlands a specialist discipline.
Can an A1 location lose its status over time?
Yes. A1 locations can and do lose their status when the structural conditions that created them shift. The Dutch retail landscape has seen meaningful polarisation over the past decade, with the strongest locations consolidating their position while weaker streets have declined. Even streets that held A1 status for decades can slip to A2 or lower if footfall patterns change, anchor tenants depart, or competing retail destinations draw shoppers away.
The drivers of location decline are recognisable. A major anchor tenant closing without replacement, a new shopping centre opening in the same catchment, a change in urban planning that redirects pedestrian flow, or a sustained rise in vacancy that signals weakening retailer confidence can all initiate a downgrade. E-commerce has accelerated this dynamic by reducing the total volume of physical retail visits, concentrating remaining footfall into fewer, stronger locations.
In the Netherlands specifically, the difference between a location that holds its A1 status and one that loses it can be stark. Dutch consumers are pragmatic shoppers. If a street no longer offers the brands and experience they want, they will travel further to a stronger location or shift to online alternatives. This means that marginal A1 streets, those that were borderline to begin with, carry real structural risk that is not always visible in historical rent data.
For investors, the key question is not just whether a location is classified as A1 today but whether the conditions that support that classification are durable. That requires an assessment of the catchment, the competitive retail environment, the tenant mix, and the pipeline of potential occupiers. It is precisely the kind of analysis that distinguishes a specialist advisor from a generalist broker. KroesePaternotte’s retail investment advisory is built around this kind of forward-looking location assessment, drawing on four decades of transaction data and active daily engagement with retailers, landlords, and developers across the Netherlands.
International investors who want to understand the full picture of where Dutch retail real estate is heading, and which locations are genuinely defensible, can explore the breadth of KroesePaternotte’s market expertise or visit kroesepaternotte.com directly.
Related Articles
- What are typical cap rates for Dutch retail property?
- How long can you temporarily rent a retail space in the Netherlands?
- What due diligence is needed for Dutch retail property investment?
- What are the risks of expanding too quickly with multiple stores?
- What is an A1 location in the Netherlands?
- What is an anchor tenant in Dutch retail real estate?
- What is yield compression in Dutch retail real estate?
- How does e-commerce affect Dutch retail real estate?
- How do PDV and GDV locations work in the Netherlands?